
"Stayin' Alive" by the Bee Gees may suggest disco dancing your way through the streets of New York more than considering healthcare deductibles and Medicare enrollment, but the title lends itself with a bit of levity to a conversation about healthcare. After all, staying healthy, active, and, yes, alive is kind of the whole point of healthcare.
The chorus is all about keeping going, adapting, and making it through whatever comes our way. Healthcare planning follows a similar rhythm. As life changes, our healthcare needs change, too, and our plans need to be ready to change right along with them.
Healthcare affects more than our physical well-being – it can also have a meaningful impact on our financial health. From managing everyday medical expenses to preparing for Medicare and the possibility of long-term care, the decisions we make along the way can have a lasting effect on our financial picture.
Planning ahead can help you understand your options, anticipate potential costs, and make thoughtful decisions before they become urgent. Taking the time to prepare today can give you greater flexibility and confidence as your healthcare needs evolve in the years ahead.
Healthcare is one of the few financial considerations that follows us through every stage of life. The decisions that make sense in your 30s may look very different in your 60s or 80s.
While everyone's situation is different, thinking ahead can help you make more informed decisions, avoid unnecessary costs, and better prepare for the healthcare expenses that may come with each stage of life.
Before Age 50: Build the Foundation
For many people, the working years are an opportunity to take advantage of employer-sponsored benefits and build a strong foundation for future healthcare costs.
If you are eligible for a Health Savings Account (HSA), consider making it part of your long-term savings strategy. HSAs can offer a unique tax advantage: contributions may be tax-deductible, investment growth can be tax-free, and withdrawals used for qualified medical expenses can generally be tax-free. The account is also portable, meaning it stays with you if you change employers or leave the workforce.
Other important considerations during your working years include:
- Reviewing your health insurance options during each open enrollment period
- Taking advantage of employer benefits, including wellness programs and flexible spending accounts when appropriate
- Maintaining adequate disability insurance to protect your income if an illness or injury prevents you from working
- Completing preventative care and regular screenings rather than waiting for a health issue to arise
- Establishing healthcare directives and powers of attorney so someone you trust can make healthcare decisions if you are unable to do so
The goal during these years is simple: protect your current health and income while building resources that can help with future healthcare costs.
Age 50–64: Prepare for the Transition
As retirement gets closer, healthcare planning becomes increasingly important. If you plan to retire before 65, one of the biggest questions is how you will maintain health coverage until Medicare begins. Depending on your circumstances, options may include COBRA, a spouse's employer plan, or private coverage through the Health Insurance Marketplace.
This can also be an important time to revisit your savings strategy. Building an after-tax pool of assets can provide additional flexibility for early retirement expenses, including healthcare, without relying exclusively on retirement accounts.
If you are eligible for an HSA, remember that you can generally make an additional contribution beginning at age 55. Once you enroll in Medicare, however, you can no longer contribute to an HSA.
This is also the time to consider long-term care insurance. Traditional long-term care insurance may not be the right fit for everyone, but it is not the only option. Hybrid policies, for example, can combine long-term care coverage with a life insurance death benefit, providing a way to address potential care needs while offering a benefit to your beneficiaries if long-term care is never needed.
Age 65: Medicare Begins
Turning 65 brings a major change in how healthcare is funded. Medicare has several moving pieces, including Part A, Part B, Part D, Medicare Advantage, and Medigap.
Your Initial Enrollment Period generally begins three months before your 65th birthday month and ends three months after it. Missing the appropriate enrollment window can result in delayed coverage and, in some circumstances, late-enrollment penalties.
Choosing coverage should go beyond simply comparing premiums. Consider:
- Your current doctors and whether they participate in the plan
- Prescription medications and coverage
- Your expected healthcare needs
- Premiums, deductibles, copays, and out-of-pocket costs
- Whether you prefer Original Medicare with supplemental coverage or a Medicare Advantage plan
- How your choice works with a spouse's coverage or other insurance
Income can also affect Medicare costs. Medicare generally uses tax-return information from two years earlier when determining whether higher-income beneficiaries will pay an Income-Related Monthly Adjustment Amount, or IRMAA. That makes tax planning in the years surrounding Medicare enrollment particularly important.
Medicare is a major piece of the healthcare puzzle, but it is not designed to cover every type of care you may need later in life.
Age 70–90+: Plan for Long-Term Care
As we age, the conversation often shifts from health insurance to how care will actually be provided.
Long-term care can include assistance with everyday activities such as bathing, dressing, eating, or moving around. It may be provided at home, through community services, in an assisted living facility, or in a nursing home. Medicare generally does not cover this type of ongoing custodial care.
Planning ahead means thinking about more than just the cost. Consider:
- Would you prefer to remain in your home as long as possible?
- Could your home be modified to make aging in place easier?
- Who would help coordinate your care?
- What would assisted living or a continuing care community look like?
- How would you pay for care that isn't covered by Medicare?
- Do you have long-term care insurance or another source of dedicated funding?
- Have you documented your healthcare wishes and identified someone you trust to make decisions on your behalf?
These conversations can be difficult to have, but planning before a crisis gives you and your family more choices. The goal isn't necessarily to predict exactly what type of care you will need. It's to understand your options and build a financial plan that gives you flexibility if those needs arise.
Healthcare Is a Lifelong Planning Conversation
Healthcare planning doesn't have a single finish line. It evolves as your health, employment, family, and financial circumstances change.
Whether you're maximizing an HSA in your working years, planning for healthcare before Medicare, evaluating your Medicare options at 65, or preparing for potential long-term care later in life, the most valuable step is often simply to start the conversation before you need to make a decision under pressure.
Jordan's Journal
Markets delivered another positive quarter, though September was a reminder that the path is rarely smooth. The S&P 500 finished the quarter up roughly 12% year to date and remains within a few percent of its all-time high. Importantly, these gains continue to reflect real earnings growth: 86% of companies beat expectations in the second quarter, one of the highest rates on record, and 8 of 11 sectors posted double-digit earnings growth. AI remains a major driver, with earnings at AI infrastructure companies growing 54% year-over-year, compared with roughly 14% for the rest of the market. That enthusiasm has come with plenty of volatility. Semiconductor stocks fell 29% in about five weeks this summer as leveraged hedge funds unwound positions, before rebounding sharply. Emerging markets have also remained strong, while bonds had a more difficult quarter as long-term Treasury yields climbed to their highest levels in more than two decades. Alternatives again told two different stories, with select liquid alternative strategies posting gains while bitcoin remained volatile.
Looking forward to the year-end, three storylines are worth watching.
1. Interest Rates: The Federal Reserve raised its benchmark rate by a quarter point on September 16, bringing the target range to 3.75%–4.00% and marking its first hike since 2023. Inflation remains above the Fed's 2% target, although the latest data provided some encouragement: core PCE inflation slowed to 3.0% in August from 3.3% in the prior month. At the same time, the economy continues to show resilience, which has kept pressure on long-term interest rates. The 10-year Treasury yield reached roughly 5.3% at the end of September, its highest level since 2002. Expectations for additional rate hikes may be getting ahead of the data, but the combination of persistent inflation and strong economic growth means rates may cause them to remain higher for longer. The silver lining for investors is that bonds are once again offering meaningful income, although prices of long-dated bonds have become less dependable as yields continue to rise.
2. Geopolitical Events: Geopolitical tensions pushed oil sharply higher during September, with Brent crude moving above $100 a barrel as disruptions around the Strait of Hormuz constrained global energy flows. Shipments have since partially recovered, but oil remains elevated, and the situation continues to carry implications for inflation and economic growth. The midterm elections are also now just over a month away. Historically, markets have often performed well after midterm elections as uncertainty clears, but the more immediate volatility may continue to rear its head until then.
3. Concentration: AI-related companies now represent a very large share of the U.S. stock market, and the technology buildout is increasingly influencing the corporate bond market as companies borrow to finance data centers and other infrastructure. The long-term opportunity from AI remains substantial, and today's valuations are still well below the extremes reached during the dot-com era. But September offered a useful reminder that strong index performance can mask weakness underneath: the equal-weighted S&P 500 fell roughly 4% during the month while the traditional market-cap-weighted index held up much better. When a relatively small group of companies is responsible for a large share of market returns, diversification becomes increasingly important.
As always, the best course of action is to stay diligent and diversified, with your eyes focused on long-term goals, while maintaining enough liquidity for short-term spending needs.
News and Upcoming Events
More Than Money- Estate & Legacy Panel
Last month, we hosted our More Than Money: A Legacy Planning Panel, a conversation focused on the many aspects of legacy planning that go beyond simply inheriting assets.
Our panel brought together professionals who shared perspectives on estate planning, charitable giving, and preparing the next generation. We discussed the importance of family conversations, organizing your wishes, and giving your loved ones the context and tools they may need in the future.
Missed the conversation? Watch the recording here.
2026 Summer Photo Contest
Thank you to everyone who shared a little piece of their summer with us! It was so fun seeing the adventures, travels, and memories happening beyond the office. We hope these photos inspire everyone to make time for a little more fun along the way!
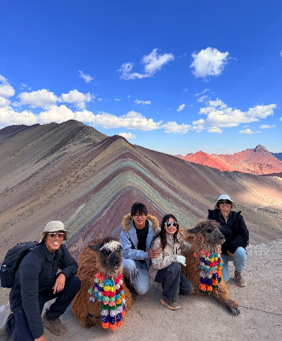
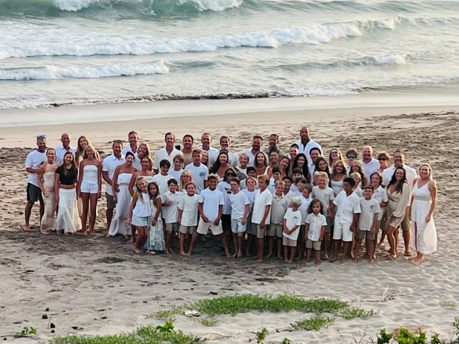
And the winner is.... Julia & Jonathan Wang and Tara & Andy Barton
Julia & Jonathan Wang - Machu Picchu, Peru | Tara & Andy Barton - 68 people from their Huntington Beach neighborhood traveled to Nicaragua on vacation |
|
|
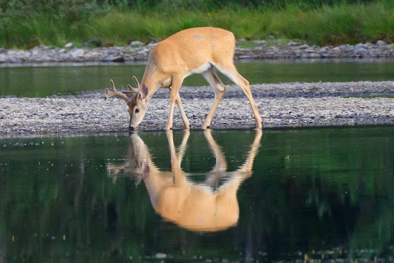
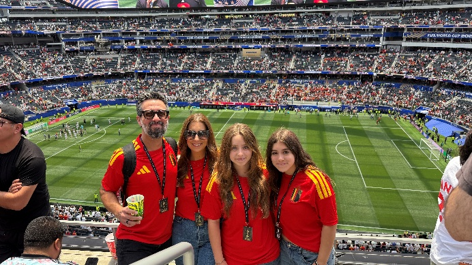
Second Place – Cheryl Lancaster and Manny & Monique Burrola
Cheryl Lancaster - Glacier National Park | Manny & Monique Burrola - First World Cup Match: Belgium vs. Iran |
|
|
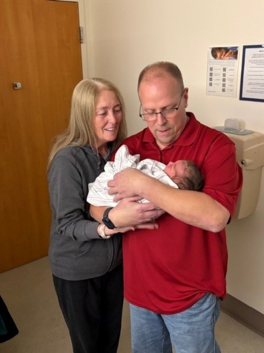
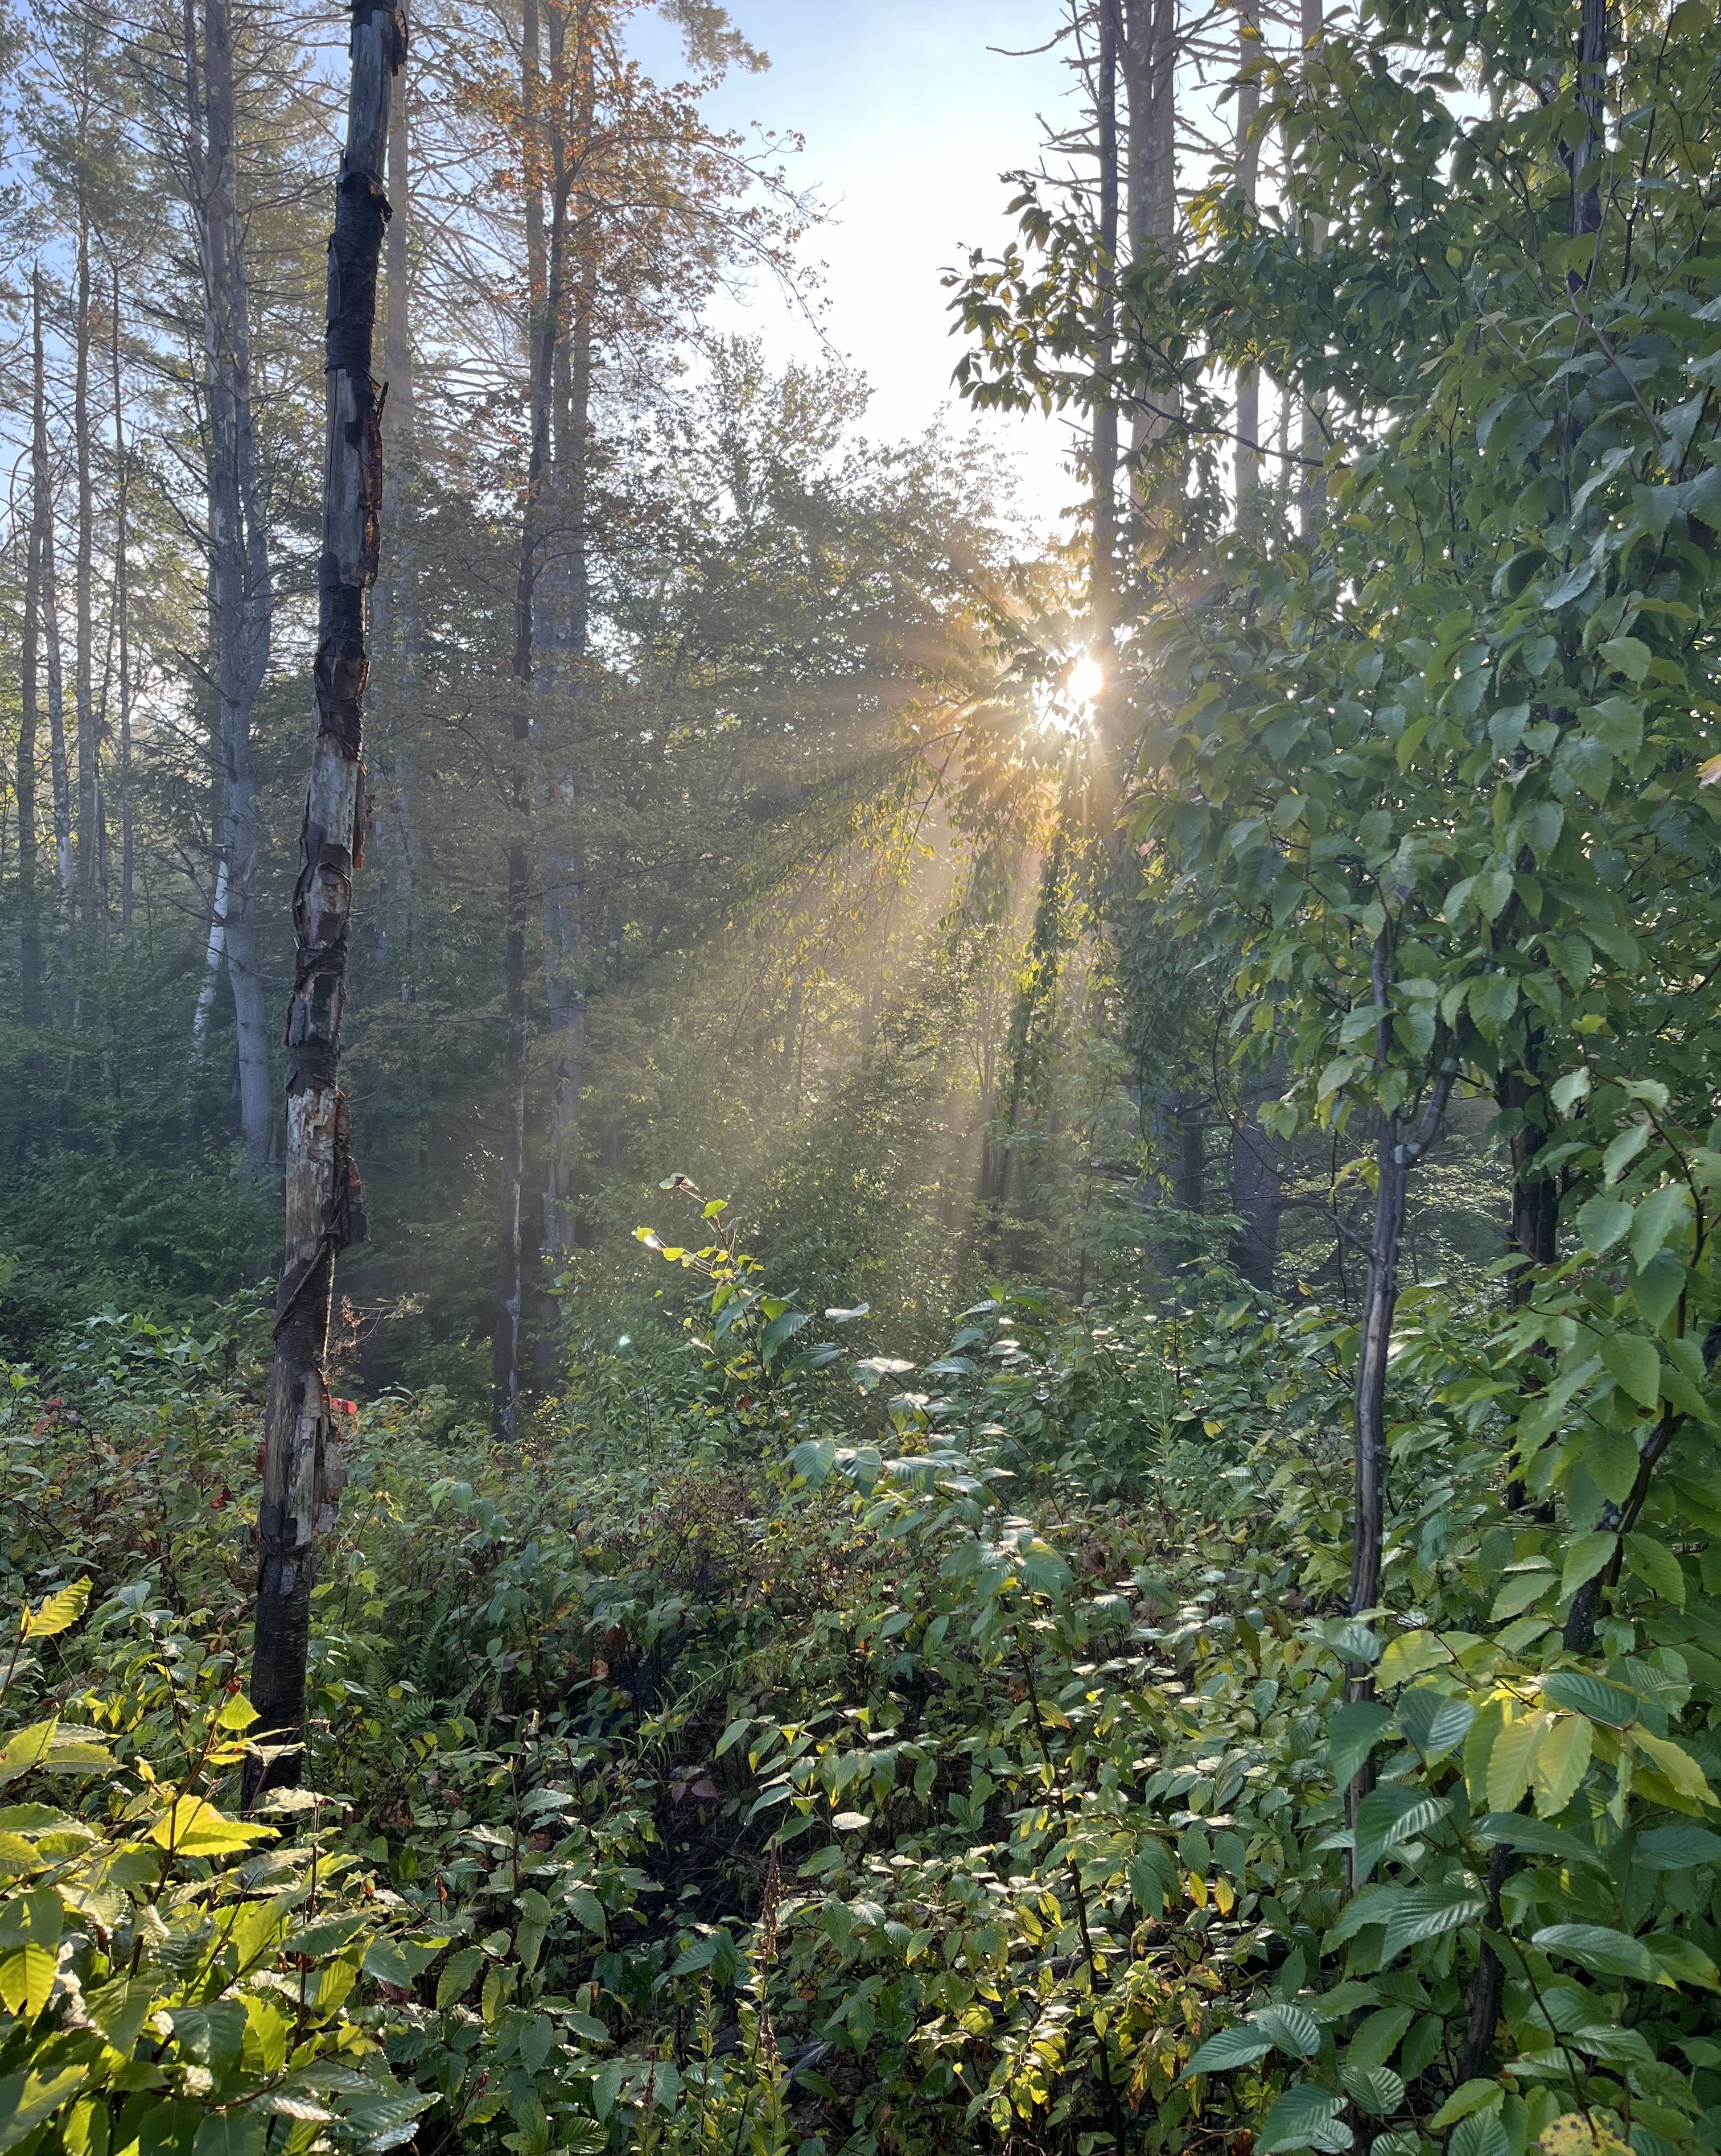
Third Place – Kim Kirkpatrick & Dave Dayter and Scott & Kim Green
Kim Kirkpatrick & Dave Dayter - Meeting their granddaughter for the first time | Scott & Kim Green - At their son's property in Vermont |
|
|
Client Appreciation Events are coming up soon!
One of our favorite traditions each year is getting together with our clients for our annual Client Appreciation Events! We’d love for you to join us for an evening of good food, great conversation, and catching up with old friends.
Our Texas Client Appreciation Event will be held at Sixty Vines Restaurant on October 7th, and our California Client Appreciation Event will take place at Spaghettini Restaurant in Seal Beach on November 5th. Questions? Reach out to Jenny at jenny@prosperitywealthplanning.com.
Prosperity Wealth Planning Travel Club
We recently launched the PWP Social & Travel Club, created to bring clients together around shared interests, experiences, and new adventures. As part of the launch, we hosted our first Travel Club presentation with Tauck Tours, highlighting two exciting travel opportunities for 2027.
Watch the PWP Travel Club Presentation to learn more about the trips.
Voice of the Client Survey
Your experience matters to us, and your feedback helps us understand what we’re doing well and where we can continue to improve. Each year, we invite you to share your thoughts through our Voice of the Client Survey.
Our annual survey will be sent on October 13th, and we’d love for you to take a few minutes to share your feedback. We genuinely enjoy hearing from you and use your input to help us continue providing the level of service you expect from our team.
Keep an eye on your inbox for the survey!
Cheers,
The Prosperity Wealth Planning Team